Saving money sounds simple until everyday expenses start getting in the way.
You may plan to save a certain amount every month, but then bills arrive, groceries cost more than expected, or you spend money on something you did not plan for. Before you realize it, the month ends and there is little or nothing left to save.
This is why automatic saving can be so useful.
Instead of waiting until the end of the month to see what money is left, you can set up a system that moves money into savings automatically. Once the system is running, saving becomes a regular part of your financial routine instead of something you have to remember every month.
In this guide, you will learn how to save money automatically every month, how much you should automate, where to keep your savings, and how to build a simple system that works even if you are a beginner.
What Does It Mean to Save Money Automatically?
Saving money automatically means setting up a recurring transfer that moves money from your main account into a savings account without requiring you to do it manually each time.
For example, you could arrange for part of your income to move into savings shortly after you get paid.
Instead of thinking:
“I will save whatever is left at the end of the month.”
You change the approach to:
“I will save first, then use the money that remains for my expenses.”
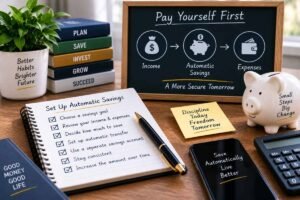
This is sometimes called paying yourself first.
The goal is not necessarily to save a large amount immediately. The goal is to make saving consistent.
The Consumer Financial Protection Bureau explains that recurring transfers can be set up through many banks and credit unions, allowing you to choose an amount and schedule for moving money into savings. Consumer Financial Protection Bureau
Even a small automatic transfer can become meaningful when you continue it month after month.
Why Automatic Saving Works
One of the biggest problems with saving manually is that it requires constant decision making.
Every month, you have to remember to transfer money, decide how much to save, and resist the temptation to spend it.
If your first goal is to build an emergency fund, you can learn how to start one step by step in our guide on how to build an emergency fund.
When money moves automatically, you do not have to rely on motivation every month.
The process becomes part of your normal financial routine.
It Reduces Unnecessary Spending
Money sitting in your everyday spending account can feel available to spend.
Moving some of it into a separate savings account can create a simple psychological barrier between your spending money and your savings.
It Helps You Reach Goals
Automatic transfers can make financial goals easier to work toward.
Whether you are building an emergency fund, saving for education, planning a trip, or preparing for a large purchase, regular contributions can keep you moving forward.
It Saves Time
Once the system is set up, you do not need to manually transfer money every month.
Your bank handles the transfer according to the schedule you choose.
How to Save Money Automatically Every Month
Setting up automatic savings does not have to be complicated.
You can start with a simple system and adjust it as your income and expenses change.
If you need a simple framework for dividing your income between needs, wants, and savings, you can learn more about the 50/30/20 budget rule.
Here is a step by step approach.
1. Choose a Specific Savings Goal
Before setting up an automatic transfer, decide what you are saving for.
A specific goal gives your savings a purpose.
For example, you might be saving for:
- An emergency fund
- A new laptop
- Education
- A future move
- A vacation
- A car
- Home related expenses
- Annual bills
- Future investments
You do not necessarily need to choose only one goal.
However, beginners may find it easier to start with one important goal before creating multiple savings accounts.
For example, if you do not have emergency savings yet, building an emergency fund could be your first priority.
2. Look at Your Monthly Income and Expenses
Before deciding how much to save automatically, understand your current cash flow.
Write down your regular monthly income and your essential expenses.
Your expenses may include:
- Rent or housing
- Food
- Transportation
- Utilities
- Phone and internet
- Debt payments
- Education
- Insurance
- Family expenses
Then look at your flexible spending, such as entertainment, shopping, eating out, and subscriptions.
This gives you a realistic idea of how much money you can comfortably move into savings.
If you want to get better control of your income and expenses, our guide on how to manage your money covers simple habits beginners can use.
The goal is to create a savings amount that you can maintain.
A transfer that is too large may leave you short of money before the end of the month.
3. Start With an Amount You Can Actually Afford
You do not need to start with a large amount.
If your budget is tight, start small.
For example, you could automatically transfer a small fixed amount after each paycheck or once a month.
The important thing is consistency.
A smaller amount that you save every month is usually more sustainable than setting an aggressive target that you cannot maintain.
Once your financial situation improves, you can increase the automatic transfer.
4. Set Up an Automatic Bank Transfer
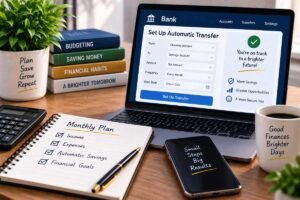
Most banks provide some type of recurring or scheduled transfer feature.
You can usually choose:
- The amount
- The transfer date
- The account receiving the money
- How frequently the transfer happens
For example, you could schedule a transfer shortly after your regular income arrives.
This timing can be useful because the money moves toward your goal before you have a chance to spend it.
The Consumer Financial Protection Bureau recommends checking the terms, conditions, and fees that may apply to recurring transfers before setting up an automatic savings system. Consumer Financial Protection Bureau
Check your bank’s current options and account terms because automatic transfer features vary between banks and countries.
5. Save Immediately After You Get Paid
One useful strategy is to schedule your automatic savings transfer soon after receiving your income.
For example, imagine your income arrives at the beginning of the month.
Instead of waiting until the end of the month, your automatic transfer could happen shortly afterward.
This follows the “pay yourself first” approach.
The idea is simple:
Income → Savings → Expenses
Rather than:
Income → Expenses → Whatever Is Left → Savings
The second approach often fails because there may be nothing left to save.
The Consumer Financial Protection Bureau notes that automatic transfers scheduled around your payday can help you consistently put money into savings before other spending takes place. Consumer Financial Protection Bureau
6. Use a Separate Savings Account
Consider keeping your savings separate from your everyday spending account.
When your savings and spending money are mixed together, it can be easier to accidentally spend money that you intended to save.
A separate account creates a clearer boundary.
For example:
Everyday account: bills, groceries, transportation, and regular spending
Savings account: emergency fund and financial goals
Depending on your goal, you may also consider a high yield savings account where available, but always compare fees, access rules, interest rates, and deposit protection before opening an account.
7. Automate Different Savings Goals
Once you become comfortable with automatic saving, you can create separate systems for different goals.
For example, you could have:
Emergency Fund
Money reserved for unexpected expenses.
Short Term Goals
Money for purchases or expenses you expect within the next few months or years.
Annual Expenses
Money for predictable expenses such as insurance, education costs, or yearly subscriptions.
Long Term Goals
Money intended for future financial goals.
Separate goals can make your progress easier to understand.
Instead of seeing one large savings balance without knowing its purpose, you know what each portion of your money is intended for.
8. Automate Your Savings When Your Income Increases
One of the easiest ways to increase your savings is to adjust your automatic transfer when your income rises.
Suppose you receive a raise, start earning more from freelancing, or increase your business income.
You do not necessarily need to increase your lifestyle spending by the same amount.
Consider directing part of the additional income toward savings.
This allows your savings rate to increase without making your regular budget feel significantly tighter.
9. Automate Savings From Irregular Income
Automatic saving can be more difficult if your income changes from month to month.
This is common for freelancers, business owners, commission based workers, and people with multiple income sources.
Instead of setting an amount that may be difficult to maintain, you could use a percentage based approach.
For example, whenever you receive income, you could move a predetermined percentage into savings.
This allows your savings contribution to increase during stronger months and decrease during weaker months.
The exact percentage should depend on your expenses, income stability, and financial goals.
10. Create a Buffer in Your Main Account
One potential problem with automatic transfers is accidentally moving too much money out of your spending account.
If your balance becomes too low, you could struggle to cover bills or other essential expenses.
To reduce this risk, consider keeping a small buffer in your main account.
This does not mean you should keep a large amount of unused cash there.
Before setting up automatic transfers, the Consumer Financial Protection Bureau recommends paying attention to your account balance so that scheduled transfers do not leave you without enough money for other expenses or cause overdraft fees. Consumer Financial Protection Bureau
The purpose is simply to provide some breathing room for unexpected timing differences between income, bills, and automatic transfers.
How Much Should You Save Automatically Each Month?
There is no single amount that works for everyone.
Your ideal automatic savings amount depends on factors such as:
- Your income
- Your essential expenses
- Your debt payments
- Your financial goals
- Your emergency savings
- Your income stability
- Your family responsibilities
If you are just starting, focus on creating a sustainable habit.
For someone with limited income, a small automatic transfer may be appropriate.
Someone with more financial flexibility may be able to save considerably more.
The important thing is to choose an amount that does not regularly force you to transfer money back out of savings.
What If You Cannot Save Much Right Now?
Do not assume that automatic saving is only useful for people with high incomes.
If money is tight, start with what you can reasonably afford.
You might begin with a very small recurring transfer and increase it later.
You can also look for ways to create additional room in your budget by reviewing subscriptions, unnecessary fees, impulse purchases, and other flexible expenses.
The purpose is not to make your budget miserable.
If your budget is tight, you can also explore these practical strategies to save money on a low income without making your budget unnecessarily difficult.
It is to create a system where some money consistently moves toward your future.
Where Should You Keep Your Automatic Savings?
The right place depends on what the money is for.
For emergency savings and short term goals, a savings account may be appropriate because the money should generally remain accessible.
For longer term goals, other financial options may be worth considering depending on your time horizon, risk tolerance, and financial situation.
Do not choose an account simply because it advertises a high interest rate.
Look at the complete picture, including:
- Interest or APY
- Fees
- Minimum balance requirements
- Withdrawal rules
- Accessibility
- Deposit protection
- Account terms
The best choice depends on your personal circumstances and the purpose of the money.
Automatic Saving vs. Manual Saving
Both methods can work, but they require different levels of effort.
Manual Saving
You decide how much to save and transfer the money yourself.
Advantages:
- More flexibility
- Easy to adjust every month
- Useful when income changes frequently
Disadvantages:
- Easy to forget
- Requires more discipline
- You may spend the money before saving it
Automatic Saving
Your bank transfers money according to a schedule.
Advantages:
- Requires less effort
- Encourages consistency
- Reduces unnecessary decisions
- Makes saving part of your routine
Disadvantages:
- Can cause cash flow problems if the amount is too high
- Requires some planning
- Needs to be reviewed when your income or expenses change
For many beginners, automation can make saving easier because it removes one more financial task from their monthly routine.
Common Automatic Saving Mistakes to Avoid
Automatic saving is simple, but there are still a few mistakes worth avoiding.
Setting the Amount Too High
Saving aggressively can look good on paper, but it can create problems if your regular expenses are not covered.
Start with a realistic amount.
Forgetting About Your Automatic Transfer
Automation does not mean you should completely ignore your accounts.
Review your transfers occasionally to make sure they still match your financial situation.
Keeping Savings Too Easy to Spend
If your savings are in the same account you use for daily spending, you may be more tempted to use them.
A separate savings account can help.
Never Increasing Your Savings
If your income increases over time, consider reviewing your automatic savings amount.
Your original transfer may no longer reflect your financial capacity.
Using Savings for Every Small Purchase
Savings should have a purpose.
If you constantly transfer money back to your spending account, your automatic savings system may need to be adjusted.
A Simple Automatic Savings System for Beginners
If you want to start today, keep the process simple.
Step 1: Choose One Goal
Pick one important financial goal.
For example, you could start with an emergency fund.
Step 2: Choose a Realistic Amount
Look at your budget and select an amount you can consistently save.
Step 3: Open or Choose a Separate Savings Account
Use an account that fits your needs and offers reasonable terms.
Step 4: Schedule the Transfer
Set up an automatic recurring transfer shortly after your income arrives.
Step 5: Leave the Money Alone
Treat the automatic transfer as part of your normal financial routine.
Step 6: Review Your Progress
Check your savings regularly.
You do not need to monitor it every day.
A monthly review is often enough for many people.
Step 7: Increase the Amount When Possible
When your income rises or your expenses decrease, consider increasing your automatic savings contribution.
How to Make Automatic Saving Even Easier
Once your basic system is working, you can make it more effective with a few simple habits.
First, give every savings account a clear purpose.
Instead of calling an account “Savings,” you could use labels such as “Emergency Fund,” “Education,” or “New Laptop.”
A clear name reminds you why you are saving.
Second, avoid checking your savings balance constantly.
Saving is a long term process. Small changes may not look impressive from week to week, but consistent contributions can add up over time.
Finally, review your system whenever something important changes in your life.
A new job, higher income, new expense, debt repayment, or major financial goal may require you to change your automatic transfer.
Final Thoughts
Learning how to save money automatically every month can make saving much easier because it turns a financial goal into a routine.
You do not have to depend entirely on willpower or remember to transfer money every month.
Start by choosing a clear goal, reviewing your budget, selecting a realistic amount, and setting up an automatic transfer soon after you receive your income.
Keep your savings separate from everyday spending when possible, review your system occasionally, and increase your contribution as your financial situation improves.
The most important part is not starting with a huge amount.
It is building a system that you can continue using month after month.
When saving becomes automatic, you can spend less time thinking about whether you saved this month and more time watching your financial goals move forward.
Frequently Asked Questions
Is automatic saving a good idea for beginners?
Automatic saving can be useful for beginners because it reduces the need to remember to transfer money manually. It can also help make saving a regular financial habit.
How often should I automatically save money?
You can save weekly, biweekly, or monthly depending on how you receive your income and manage your budget. Choose a schedule that matches your cash flow.
What if I have a low income?
You can still automate savings with a small amount that fits your budget. The goal is to create a sustainable habit rather than save an amount that causes financial stress.
Should I automate emergency savings?
Automatic transfers can be a practical way to build an emergency fund because they allow you to contribute consistently instead of waiting until the end of the month.
Should I keep my automatic savings in a separate account?
A separate savings account can make it easier to distinguish money intended for future goals from money available for everyday spending.
Can I change my automatic savings amount?
Yes. You can generally adjust your automatic transfer when your income, expenses, or financial goals change. Check your bank’s available settings and account terms.
What happens if I need the money I automatically saved?
If you need the money for a genuine expense, you can usually transfer it back if your account allows withdrawals or transfers. However, regularly taking money back out may indicate that your automatic savings amount needs to be adjusted.
What is the easiest way to start automatic saving?
Choose one savings goal, select a small amount you can comfortably afford, and schedule a recurring transfer from your main account to a separate savings account. Starting simple is often the easiest way to build the habit.