Have you ever wanted to buy something but did not have enough money to pay for it all at once? You may have seen an option at checkout that says “Buy Now, Pay Later” or “BNPL.”
Buy Now Pay Later allows you to purchase something today and pay for it over time, usually through several smaller payments. It can make a purchase feel more affordable because you do not have to pay the full cost immediately.
However, BNPL is still a form of borrowing. The fact that the payments are divided into smaller amounts does not make the purchase free or automatically affordable. Depending on the provider and plan, you may face interest, late fees, account fees, or other costs.
In this beginner’s guide, you will learn what Buy Now Pay Later is, how it works, how BNPL payments are structured, its advantages and disadvantages, and what you should consider before using it.
What Is Buy Now Pay Later?
Buy Now Pay Later is a short term financing option that allows you to purchase a product or service immediately and repay the cost over a set period.
The Consumer Financial Protection Bureau (CFPB) describes BNPL as a type of installment loan that generally allows consumers to purchase something immediately and repay the balance through several payments.
Instead of paying the entire purchase price at checkout, you may be able to split the cost into several installments.
For example, imagine you want to purchase a product that costs $200. A BNPL provider might allow you to divide the purchase into four payments of $50.
You receive the product now, while the payments are made according to the repayment schedule.
The exact terms depend on the BNPL provider. Some plans may charge no interest when payments are made on time, while others may charge interest or other fees.
This is why it is important to read the terms before accepting a BNPL plan.
How Does Buy Now Pay Later Work?
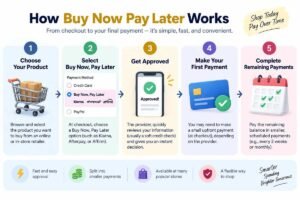
The process is usually straightforward.
Although the exact process varies between providers, BNPL generally works like this:
1. Choose Your Product
You start by shopping online or in a store and selecting the product or service you want to purchase.
At checkout, you may see several payment options, including a Buy Now Pay Later option.
2. Select BNPL
Instead of paying the full amount immediately, you select the BNPL option.
The provider may ask you to provide some personal and payment information before approving the purchase.
3. The Provider Reviews Your Application
Depending on the provider and the size of the purchase, the BNPL service may perform some form of eligibility or credit assessment.
Some providers may use a soft credit check, while others may use a hard credit inquiry. The effect on your credit report can therefore vary.
Do not assume that every BNPL service works the same way.
4. Make the Required Initial Payment
Some BNPL plans require you to make the first installment at the time of purchase.
For example, if a purchase is divided into four equal payments, you might pay the first installment immediately and the remaining payments according to the schedule.
5. Make the Remaining Payments
The remaining balance is then paid over the agreed period.
Payments may be automatically withdrawn from your debit card, bank account, or another payment method.
If you make all payments on time, the purchase is eventually paid in full.
A Simple Buy Now Pay Later Example
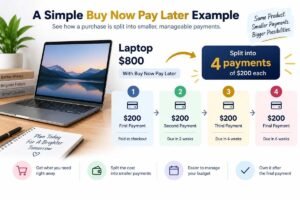
Let’s make the process easier to understand.
Suppose you want to buy a laptop for $800.
A BNPL provider offers a four-payment plan with no interest if you make every payment on time.
The purchase could be divided like this:
| Payment | Amount |
|---|---|
| First payment | $200 |
| Second payment | $200 |
| Third payment | $200 |
| Fourth payment | $200 |
| Total | $800 |
You receive the laptop immediately, but you still have three future payments to make.
This is an important point to remember.
BNPL does not make an $800 purchase cost less. It simply changes when and how you pay for it.
If fees or interest apply, the total amount you repay could be higher than the original purchase price.
What Types of Purchases Can You Make With BNPL?
BNPL services can be available for many different types of purchases.
Depending on the provider, you may see BNPL options for:
- Clothing
- Electronics
- Furniture
- Travel
- Beauty products
- Home appliances
- Online shopping
- Food delivery
- Services
- Other everyday purchases
The availability of BNPL depends on the merchant, provider, country, and type of purchase.
Some providers also place restrictions on certain products or transactions.
Does Buy Now Pay Later Charge Interest?
Sometimes, but not always.
One of the reasons BNPL has become popular is that some plans advertise zero interest when you follow the payment schedule.
However, other BNPL products can charge interest.
For example, a provider might offer different financing options depending on the purchase and your eligibility.
Even when a plan does not charge interest, there may still be other fees.
Before accepting a BNPL offer, check:
- Interest rate
- Late payment fees
- Account fees
- Payment schedule
- Total repayment amount
- What happens if you miss a payment
- Whether credit reporting is involved
The CFPB explains that BNPL plans can involve different types of BNPL fees and charges, including late fees depending on the provider and agreement.
The most important number is often the total amount you will repay, not simply the size of each installment.
What Happens If You Miss a BNPL Payment?
Missing a payment can have different consequences depending on the provider and the agreement.
You could potentially face:
- Late fees
- Account restrictions
- Collection activity
- Additional interest or charges
- Negative credit reporting in some circumstances
Some providers may also stop you from using their service until your outstanding balance is paid.
This is why you should not choose BNPL simply because the individual payments appear small.
Before using it, make sure you can comfortably afford every scheduled payment.
Does BNPL Affect Your Credit Score?
This depends on the provider and the specific BNPL product.
Some BNPL providers may not report regular payment activity to major credit bureaus, while others may report certain information.
If you’re new to credit, it’s also helpful to understand what a credit score is and why it matters before using different forms of financing.
Credit checks can also differ between providers. Some may use a soft inquiry during the application process, while others may perform a hard inquiry.
Because policies can change, check the provider’s current terms before signing up.
If building or maintaining your credit history is important to you, understand exactly how the BNPL service handles credit reporting.
If you’re trying to establish a stronger credit history, you may also want to learn how to build credit and which financial habits can help over time.
Buy Now Pay Later vs. Credit Cards
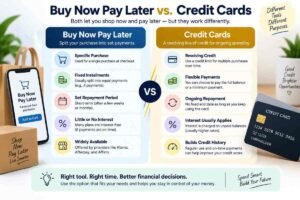
BNPL and credit cards both allow you to buy something without paying the entire amount immediately, but they work differently. If you’re unfamiliar with credit cards, learning how a credit card works can help you understand the differences between the two.
With a traditional credit card, you usually receive a revolving credit limit. You can make purchases, repay some or all of the balance, and continue using available credit.
BNPL is often structured around a specific purchase and a predetermined repayment schedule.
Here is a simple comparison:
| Feature | Buy Now Pay Later | Credit Card |
|---|---|---|
| Payment structure | Usually fixed installments | Revolving balance |
| Repayment period | Often predetermined | Usually ongoing |
| Interest | Depends on the plan | Depends on the card and balance |
| Credit check | Depends on provider | Usually part of application |
| Credit reporting | Depends on provider | Common |
| Reusable credit | Usually limited to provider terms | Usually yes |
Neither option should automatically be considered better for everyone.
The important thing is understanding the cost, repayment terms, and your ability to repay.
Advantages of Buy Now Pay Later
BNPL can have some useful features when used responsibly.
Smaller Payments
Instead of paying the full purchase price immediately, you may be able to divide it into smaller installments.
This can make a planned purchase easier to manage within a monthly budget.
Convenient Checkout
BNPL can be integrated directly into online checkout.
This means you may not need to apply for a traditional credit card to divide a purchase into payments.
Potentially Low or No Interest
Some BNPL plans offer no interest when payments are made according to the agreement.
However, always confirm the terms because not every BNPL plan is interest-free.
Predictable Repayment
Many BNPL plans have a fixed payment schedule.
Knowing how much you need to pay and when can make planning easier.
Disadvantages of Buy Now Pay Later
BNPL also comes with risks that beginners should understand.
It Can Encourage Unplanned Spending
One of the biggest concerns with BNPL is that splitting a purchase into smaller payments can make an expensive item feel cheaper than it really is.
A person may think:
“I can afford this payment.”
But the more important question is:
“Can I afford the entire purchase?”
If you repeatedly use BNPL for different purchases, several payment schedules can build up at the same time.
Multiple Payments Can Become Difficult to Track
Imagine you have four separate BNPL purchases.
Each one may have its own payment dates.
A few small payments can quickly become a significant monthly obligation.
If you forget one of the payment dates, you could face fees or other consequences.
Late Payments Can Be Costly
A missed payment can result in fees or other problems depending on the provider.
If you are already struggling with your budget, adding another repayment obligation can make the situation worse.
It Can Hide the Real Cost of Spending
A product that costs $600 still costs $600 even if the checkout page shows several smaller payments.
The smaller payment can make the purchase psychologically easier to accept.
That does not mean the purchase is actually affordable.
Is Buy Now Pay Later Safe?
BNPL itself is not necessarily good or bad.
Its usefulness depends largely on the terms of the plan and how you use it.
A financially responsible approach is to treat BNPL as a payment method, not extra income.
If you already have enough money available to cover the purchase and are simply using an interest-free installment option for convenience, the situation is very different from using BNPL because you cannot afford the item at all.
Before using BNPL, ask yourself:
- Do I actually need this purchase?
- Can I afford the full cost?
- What is the total amount I will repay?
- Are there interest charges?
- Are there late fees?
- When are the payments due?
- Am I already paying other installment plans?
- What happens if I miss a payment?
These questions can help you make a more informed decision.
When Should You Avoid Buy Now Pay Later?
BNPL may not be appropriate when you are already struggling to cover essential expenses.
For example, if your income is barely enough to cover rent, food, utilities, transportation, and other necessities, adding another payment may create additional financial pressure.
You should also be careful if you are using BNPL repeatedly for things you do not need.
A useful rule is simple:
Do not use BNPL to make an unaffordable purchase look affordable.
If you cannot comfortably make the future payments, postponing the purchase may be a safer approach.
If you’re already dealing with existing debt, adding another payment may make your finances harder to manage. In that situation, learning how to pay off debt faster may be more useful than taking on another installment plan.
How to Use Buy Now Pay Later Responsibly
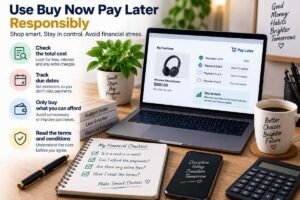
Before using a BNPL plan, it’s important to understand the total cost, payment schedule, and BNPL plan costs and risks before agreeing to the terms.
If you decide to use BNPL, a few habits can help you stay in control.
Check the Total Cost
Do not focus only on the installment amount.
Look at the total amount you will pay, including interest and applicable fees.
Read the Payment Schedule
Know exactly when each payment is due.
Put the dates on your calendar or use reminders so you do not accidentally miss one.
Keep Track of All BNPL Purchases
If you use multiple BNPL services, keep a simple list of:
- Purchase
- Total balance
- Payment amount
- Due date
- Remaining payments
This gives you a clear picture of your future obligations.
Avoid Stacking Too Many Plans
Having several installment plans at the same time can make your finances harder to manage.
One small payment may not seem significant, but several payments can add up.
Keep Emergency Savings Separate
Do not assume that future income will always arrive exactly when expected.
Having emergency savings can provide some protection when unexpected expenses appear.
Is Buy Now Pay Later the Same as a Loan?
BNPL is generally a form of financing, but the exact legal and financial structure depends on the provider and product.
Some BNPL arrangements function similarly to short-term installment financing, while others have different structures.
The important thing for consumers is to understand that you are taking on an obligation to pay in the future.
Even if the checkout process feels simple, you should still treat the agreement seriously.
What Should You Look for Before Choosing a BNPL Plan?
Before accepting any BNPL offer, compare the important terms rather than choosing the option with the smallest advertised payment.
Look at:
Total repayment: How much will you actually pay?
Interest: Is the plan interest-free or does it charge interest?
Fees: Are there late fees or other charges?
Payment frequency: Are payments weekly, biweekly, or monthly?
Repayment period: How long will you be making payments?
Credit reporting: Does the provider report payments or missed payments to credit bureaus?
Refund policy: What happens to your BNPL agreement if you return the product?
Late payment consequences: What happens if you cannot make a payment on time?
Understanding these details can prevent unpleasant surprises later.
Frequently Asked Questions About Buy Now Pay Later
Is Buy Now Pay Later free?
Not necessarily. Some plans may have no interest when payments are made on time, but other plans can charge interest or fees. Always check the specific terms.
Does BNPL build credit?
It depends on the provider. Some BNPL services may report payment activity to credit bureaus, while others may not.
Can I use BNPL if I have no credit history?
Some BNPL providers may consider applications from people with limited credit histories, but approval requirements vary.
What happens if I cannot pay my BNPL installment?
The consequences depend on the provider. You may face late fees, account restrictions, collection activity, or credit reporting in some circumstances.
Is BNPL better than using a credit card?
There is no universal answer. Compare the interest, fees, repayment schedule, credit impact, and your own ability to repay before choosing.
Can BNPL help with budgeting?
It can make a planned expense easier to spread across multiple pay periods, but it can also make overspending easier. It should be included in your budget like any other financial obligation.
Final Thoughts
Buy Now Pay Later can be a convenient way to spread the cost of a purchase across several payments. Instead of paying the entire amount at checkout, you make smaller payments according to a predetermined schedule.
But there is an important distinction to remember: BNPL does not increase your income or make an expensive purchase cheaper. It simply allows you to pay for the purchase over time.
Used carefully, an interest free BNPL plan with manageable payments may be convenient for some purchases. Used without a budget, however, multiple installment payments can quickly become difficult to manage.
Before choosing BNPL, look beyond the small payment shown at checkout. Check the total cost, interest, fees, payment dates, credit reporting policies, and consequences of missing a payment.
Most importantly, ask yourself whether you could comfortably afford the purchase without BNPL.
That simple question can help you keep installment payments from turning into unnecessary financial stress.