Learning how to improve credit utilization ratio can make managing your credit cards much easier, especially if you are a beginner. Your credit utilization ratio is one of the factors that can play a role in your credit score, and understanding how it works can help you make smarter decisions about your credit card balances.
The good news is that improving your credit utilization ratio does not usually require complicated financial strategies. In many cases, you can improve it by changing how much of your available credit you use and when you make your payments.
For beginners, the concept may sound confusing at first. What percentage should you use? Should you stop using your credit card completely? Does paying your balance before the due date help?
This guide explains how to improve your credit utilization ratio step by step. You will learn what credit utilization means, how it is calculated, why it matters, and practical ways to lower it without closing your credit cards.
What Is a Credit Utilization Ratio?
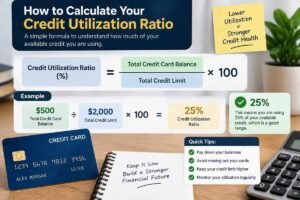
It is usually expressed as a percentage.
For example, suppose your credit card has a credit limit of $1,000 and your current balance is $300.
Your credit utilization would be:
$300 ÷ $1,000 × 100 = 30%
So, your credit utilization ratio is 30%.
If you have multiple credit cards, your overall utilization can also be calculated using the combined balances and combined credit limits.
For example:
| Credit Card | Credit Limit | Balance |
|---|---|---|
| Card A | $1,000 | $200 |
| Card B | $2,000 | $300 |
| Card C | $2,000 | $500 |
| Total | $5,000 | $1,000 |
Your overall utilization is:
$1,000 ÷ $5,000 × 100 = 20%
This is why looking only at one credit card may not give you the complete picture.
Why Does Credit Utilization Matter?
Credit utilization is one factor considered in many credit scoring models, so understanding how credit scores work can help you see why utilization matters.
Generally, using a large portion of your available credit can indicate that you are relying heavily on your revolving credit. A lower utilization ratio can be viewed more positively by credit scoring models.
For example, someone with a $5,000 total credit limit and a $4,500 balance is using 90% of their available credit.
Another person with the same credit limit but a $500 balance is using only 10%.
Both people have the same total credit limit, but their utilization is very different.
This does not mean that everyone with high utilization automatically has poor credit. Credit scores consider multiple factors, and different scoring models can calculate things differently.
However, keeping your balances relatively low can be a useful part of responsible credit management.
What Is a Good Credit Utilization Ratio?
You may have heard that you should always keep your credit utilization below 30%.
The 30% figure is commonly used as a simple guideline, especially for beginners. However, it should not be treated as a magic number.
For example, there is a meaningful difference between:
- 80% utilization
- 50% utilization
- 30% utilization
- 10% utilization
- 0% utilization
Generally, lower utilization is preferable from a credit-scoring perspective, assuming you are still using credit responsibly.
The important thing is not to become obsessed with hitting one exact percentage. Instead, focus on keeping your balances manageable and paying your bills on time.
9 Ways to Improve Credit Utilization Ratio
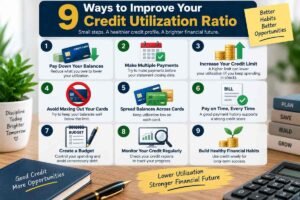
Now let’s look at practical strategies you can use to reduce your credit utilization.
1. Pay Down Your Credit Card Balances
The most straightforward way to improve your utilization ratio is to reduce your credit card balances.
Remember the basic formula:
Credit Utilization = Credit Card Balance ÷ Credit Limit × 100
If your balance decreases while your credit limit stays the same, your utilization decreases.
For example, imagine your credit card has a $2,000 limit.
If your balance is $1,000, your utilization is:
$1,000 ÷ $2,000 × 100 = 50%
If you reduce the balance to $400, your utilization becomes:
$400 ÷ $2,000 × 100 = 20%
You do not necessarily need to pay the entire balance immediately if doing so would put pressure on your budget.
Instead, create a realistic repayment plan and consistently reduce the balance.If you are dealing with multiple debts, learning how to pay off debt faster can also help you reduce your overall financial burden.
2. Make Payments Before the Statement Closing Date
Many beginners assume that only the payment due date matters.
The due date is extremely important because missing payments can have serious consequences. However, the balance reported to credit bureaus may be based on information provided around your statement cycle.
This means you could pay your credit card in full by the due date but still have a relatively high balance reported if you regularly make large purchases during the billing cycle.
One possible strategy is to make an additional payment before your statement closing date.
For example, suppose your card has a $1,000 limit and you have spent $700 during the month.
Instead of waiting until the due date, you could make a payment that reduces the reported balance before the statement is generated.
The exact reporting practices can vary between lenders, so check your card issuer’s statement cycle and reporting information.
3. Make Multiple Payments During the Month
You do not have to wait until the end of the billing cycle to make a credit card payment.
Some people find it easier to make multiple smaller payments throughout the month.
For example, instead of spending throughout the month and making one large payment later, you could make payments after receiving income or after paying for larger purchases.
This can help prevent your balance from building up too much.
It can also make your credit card easier to manage because you are regularly bringing the balance down.
However, remember that making multiple payments does not replace the need to pay at least the required amount by the due date.
4. Ask Your Credit Card Issuer for a Higher Credit Limit
Another way to reduce your utilization ratio is to increase your available credit.
For example, imagine you have:
$1,000 credit limit + $500 balance = 50% utilization
If your credit limit increases to $2,000 while the balance remains $500:
$500 ÷ $2,000 × 100 = 25% utilization
Your utilization has decreased even though your balance did not change.
However, requesting a higher credit limit does not guarantee approval. Your card issuer may review factors such as your income, payment history, existing debt, and account history.
You should also avoid requesting a higher limit simply to spend more.
If a higher limit causes you to take on additional debt, the strategy can work against your overall financial goals.
5. Avoid Closing Old Credit Cards Without a Reason
If you have an older credit card that you rarely use, you might consider closing it.
Before doing that, understand that closing a credit card can reduce your total available credit.
For example, suppose you have two cards:
- Card A: $2,000 limit
- Card B: $3,000 limit
Your total available credit is $5,000.
If you close Card B, your available credit could fall to $2,000.
If you still have a $1,000 balance on Card A, your utilization could change from:
$1,000 ÷ $5,000 = 20%
to:
$1,000 ÷ $2,000 = 50%
The impact of closing an account can depend on your overall credit profile and scoring model.
So, do not automatically close an old card just because you are not using it frequently. Consider fees, account terms, spending habits, and your overall financial situation first.
6. Spread Your Spending Across Multiple Cards
If you have multiple credit cards, concentrating all your spending on one card can cause that card’s utilization to become very high.
For example, imagine you have two cards:
- Card A: $2,000 limit
- Card B: $3,000 limit
If you put $1,800 on Card A and almost nothing on Card B, Card A has 90% utilization.
Your overall utilization may still be lower because you have unused credit available on Card B, but the individual card utilization is high.
If appropriate for your budget and financial habits, spreading normal spending across cards can prevent one card from becoming heavily utilized.
However, do not open or use additional credit cards simply to increase available credit if you are struggling to control your spending.
The goal should be better credit management, not more debt.
7. Avoid Maxing Out Your Credit Cards
Using nearly your entire credit limit can result in very high utilization.
For example, if your credit card has a $1,000 limit and your balance reaches $950, your utilization is 95%.
Even if you plan to pay the balance later, a high balance can potentially be reported during the billing cycle.
Instead of treating your credit limit as money you have available to spend, think of it as a borrowing limit that you should rarely need to approach.
A credit card should support your financial plan rather than become an extension of your income.
8. Create a Budget for Credit Card Spending
One of the best ways to control utilization is to control the spending that creates the balance in the first place.
Start by reviewing your monthly expenses.
Separate them into categories such as:
- Housing
- Food
- Transportation
- Utilities
- Subscriptions
- Entertainment
- Shopping
- Other personal expenses
Then decide how much of your spending can realistically go on your credit card.
For example, if your monthly budget allows you to spend a certain amount on groceries and transportation, use your credit card within those limits rather than spending based on the available credit limit.
This simple change can prevent your credit card balance from growing faster than you can repay it.
Creating a realistic budget is also an important part of learning how to manage your money and keep your credit card spending under control.
9. Pay Your Credit Card on Time Every Month
Credit utilization is important, but it is not the only part of your credit profile.
Your payment history is also important.
That means lowering your utilization while repeatedly missing payment deadlines is not a good strategy.
Make your payments on time and at least meet the required minimum payment.
If possible, paying the full statement balance can help you avoid interest charges on purchases when your card’s terms provide a grace period.
Setting up automatic payments can also reduce the risk of accidentally missing a due date.
How to Calculate Your Credit Utilization Ratio
Calculating your utilization is simple.
Use this formula:
Credit Utilization = Total Credit Card Balances ÷ Total Credit Limits × 100
Let’s use another example.
Suppose you have:
- Card A: $1,500 limit and $300 balance
- Card B: $2,500 limit and $500 balance
- Card C: $1,000 limit and $200 balance
Your total balance is:
$300 + $500 + $200 = $1,000
Your total credit limit is:
$1,500 + $2,500 + $1,000 = $5,000
Now calculate:
$1,000 ÷ $5,000 × 100 = 20%
Your overall credit utilization is 20%.
You can repeat this calculation whenever you want to check how much of your available revolving credit you are using.
Individual vs. Overall Credit Utilization
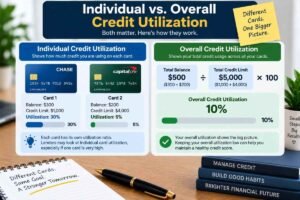
There are two numbers worth paying attention to.
Individual Card Utilization
This looks at the balance on a specific credit card compared with that card’s credit limit.
For example:
$800 balance ÷ $1,000 limit = 80% utilization
Overall Credit Utilization
This considers all your revolving credit accounts together.
For example:
$1,000 total balances ÷ $5,000 total limits = 20% utilization
Both can provide useful information about how heavily you are using credit.
This is one reason it can be helpful to review each credit card instead of looking only at your overall percentage.
Does Paying Your Credit Card in Full Improve Credit Utilization?
Paying your credit card in full can be an excellent financial habit.
However, there is an important distinction between your statement balance, current balance, and what gets reported to credit bureaus.
If you regularly make purchases throughout the month, your reported balance may not always be zero even if you eventually pay the entire statement balance.
For people who want to keep reported utilization lower, making an additional payment before the statement closing date may help.
But you should not carry a balance or pay unnecessary interest just to build credit.
You generally do not need to pay interest to establish responsible credit behavior.
Does Having 0% Utilization Help?
It may seem logical that 0% utilization must always be the goal.
However, you do not need to stop using your credit cards completely just to maintain a low utilization ratio.
A better approach is to use credit responsibly, keep balances manageable, and pay your bills on time.
Also remember that credit utilization can change from month to month.
A higher balance in one month does not necessarily mean your credit profile will remain that way permanently. As your reported balances change, your utilization can change too.
Common Credit Utilization Mistakes Beginners Should Avoid
If you are working on your credit overall, learning how to build credit fast can help you develop better credit habits over time.
Several mistakes can make it harder to manage your utilization.
Treating Your Credit Limit Like Income
A credit limit is not extra income.
It represents the amount you may be able to borrow under your card’s terms.
Only spend what you can reasonably repay.
Carrying a Balance Just to Build Credit
You do not generally need to carry a balance and pay interest to demonstrate responsible credit use.
If your card terms allow it, paying your statement balance in full can help you avoid interest on purchases.
Closing Cards Without Understanding the Consequences
Closing a card can reduce your total available credit and may affect your utilization.
Consider the broader impact before closing an account.
Focusing Only on the 30% Rule
The 30% figure is a useful guideline, but credit scoring is more complicated than one percentage.
Instead of thinking, “I am under 30%, so everything is perfect,” look at your complete credit management habits.
Ignoring High Interest Debt
If your credit card balance is growing because you cannot afford to pay it down, the bigger issue may be the debt itself.
Reducing utilization is useful, but creating a sustainable repayment plan should also be a priority.
A Simple Credit Utilization Plan for Beginners
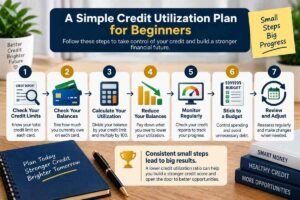
If you are just starting to manage your credit, you can follow this simple process.
Step 1: Find your credit limits
Check the credit limits on all your credit cards.
Step 2: Find your current balances
Write down the balance on each card.
Step 3: Calculate your utilization
Divide your total balances by your total credit limits and multiply by 100.
Step 4: Identify your highest-utilization card
Check whether one card is using a much larger percentage of its limit than the others.
Step 5: Create a repayment plan
Prioritize paying down balances while continuing to meet all required payments.
Step 6: Monitor your statement dates
Understand when your card issuer generates your statement and when balances may be reported.
Step 7: Build better spending habits
Use a budget so your credit card balance does not grow beyond what you can comfortably repay.
Step 8: Review your progress
Check your balances regularly and recalculate your utilization as your debt decreases.
Final Thoughts
Learning how to improve your credit utilization ratio is an important step for anyone who is beginning to build and manage credit.
The basic idea is simple: use a smaller portion of your available revolving credit and avoid allowing credit card balances to grow beyond what you can comfortably repay.
Start by calculating your current utilization. Then focus on paying down balances, making payments on time, controlling new spending, and understanding when your credit card balance may be reported.
You do not need complicated strategies to get started. Consistent habits can make credit management much easier over time.
Most importantly, remember that credit utilization is only one part of your overall credit profile. Responsible credit management also means paying bills on time, keeping debt under control, and using credit as a financial tool rather than relying on it to cover expenses you cannot afford.