Saving money is one of the most important steps toward building financial stability, but simply putting your money into a savings account does not mean you are getting the most from it. Different savings accounts can offer different interest rates, fees, minimum balance requirements, and features.
This is where a high yield savings account can become useful.
A high yield savings account is designed to pay a higher interest rate than many traditional savings accounts. That means your savings can earn more interest while remaining in an account designed for saving rather than everyday spending.
However, choosing an account should not be based on the highest advertised rate alone. A slightly higher APY may not be useful if the account has expensive fees, difficult withdrawal rules, a high minimum balance, or other requirements you cannot meet.
In this guide, you will learn how to choose a high yield savings account for beginners, what APY means, which fees to check, why minimum balances matter, how to compare different accounts, and what to look for before moving your savings.
What Is a High Yield Savings Account?
A high yield savings account is a savings account that generally offers a higher interest rate than a standard savings account.
The basic idea is simple.
You deposit money into the account, and the financial institution pays you interest for keeping your money there.
For example, imagine you have money set aside for an emergency fund. Instead of keeping all of it in an account that pays very little interest, you may be able to place it in a savings account offering a higher APY.
Your original savings remain yours, while the account can generate additional interest over time.
The exact rates offered by banks can change, so you should always check the current APY and account terms before opening an account.
What Does APY Mean?
One of the most important terms to understand when comparing savings accounts is APY, which stands for Annual Percentage Yield.
APY tells you how much you could earn from an account over one year, taking compounding into consideration. This makes APY particularly useful when comparing savings accounts with different interest rates or compounding schedules.
For beginners, the easiest way to think about it is:
Higher APY = potentially more interest earned on your savings.
However, APY should not be the only thing you consider.
A bank may advertise an attractive APY while also having requirements that make the account less suitable for you.
When comparing deposit accounts in the U.S., financial institutions are required to disclose information such as APY, interest rates, minimum balance requirements, and fees, making it easier to compare account terms. CFPB: Truth in Savings Regulation
That is why you should compare the complete account rather than focusing on one number.
Why Should Beginners Consider a High Yield Savings Account?
A high yield savings account can be useful when you want your money to remain relatively accessible while also earning interest.
It can be suitable for goals such as:
- Building an emergency fund
- Saving for a major purchase
- Setting aside money for upcoming expenses
- Building a short term savings fund
- Keeping cash that you do not need for everyday spending
The main benefit is that your savings can potentially earn more interest while sitting in the account.
If you are still building your savings, learning how to build an emergency fund from scratch can help you create a financial safety net for unexpected expenses.
However, a savings account is not designed to replace every other financial tool. Money needed for daily purchases may be better kept in an account designed for regular transactions.
7 Things to Check Before Choosing a High Yield Savings Account
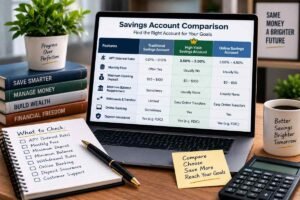
Now that you understand the basics, let’s look at the most important factors to compare.
1. Compare the APY
Start by checking the APY.
If two accounts have similar features, the account with the higher APY may allow your savings to earn more interest.
But remember that savings rates can change. Do not assume that today’s advertised APY will remain unchanged forever.
Also check whether the advertised APY applies to your entire balance or only to certain balance levels.
Financial institutions are required under U.S. deposit-account disclosure rules to provide information about APY, interest rates, minimum balance requirements, and fees, which makes comparing account terms easier.
2. Check Monthly Fees
Fees can quietly reduce the benefit of a high interest rate.
For example, suppose an account pays a competitive APY but charges a monthly maintenance fee that you cannot avoid. That fee could reduce the amount you actually gain from the account.
Before opening an account, look for:
- Monthly maintenance fees
- Excess withdrawal fees
- Transfer fees
- Account closure fees
- Other service charges
The Consumer Financial Protection Bureau recommends comparing account fees and understanding how you can avoid them.
The Consumer Financial Protection Bureau explains that banks and credit unions may charge monthly maintenance fees, although some accounts waive them when certain requirements are met. CFPB: Monthly Maintenance Fees
For beginners, a savings account with no monthly maintenance fee can be easier to manage.
3. Look at the Minimum Opening Deposit
Some accounts require a minimum amount of money to open.
For example, one account might allow you to open an account with a small deposit, while another might require a larger initial amount.
If you are just starting to save, a large minimum deposit may make an account less convenient.
Do not assume that a higher minimum automatically means a better account.
Choose an account that fits your current financial situation.
4. Check the Minimum Balance Requirements
Minimum balance requirements can be different from the minimum amount needed to open an account.
An account might allow you to open it with a small deposit but require you to maintain a certain balance to receive the advertised APY or avoid a fee.
This distinction is important.
Always check:
What balance do I need to open the account?
and:
What balance do I need to earn the advertised APY or avoid fees?
U.S. deposit account rules require relevant minimum balance requirements to be disclosed, including requirements connected to earning the advertised APY or avoiding certain fees.
5. Understand Withdrawal and Transfer Rules
A savings account is generally intended for saving rather than frequent everyday transactions.
Some financial institutions may limit certain withdrawals or transfers or charge fees when customers exceed specified limits.
Before opening an account, understand how easily you can access your money.
Ask:
- Can I transfer money online?
- How long do transfers usually take?
- Are there withdrawal limits?
- Are there fees for certain withdrawals?
- Can I transfer money to my checking account?
Your emergency savings should be accessible when you genuinely need them.
The Consumer Financial Protection Bureau notes that banks and credit unions can set limits or charge fees for certain withdrawals and transfers from savings accounts. CFPB: Savings Account Withdrawal Fees
6. Check Whether the Bank Is Insured
This is one of the most important things to check before depositing your savings.
For U.S. readers, deposits at FDIC-insured banks are generally insured up to the applicable legal limit, subject to the FDIC’s rules and ownership categories. The FDIC provides tools for checking whether a bank is insured.
If you live outside the United States, the relevant protection will depend on your country.
For example, your country may have its own deposit insurance organization.
Do not assume that every financial platform offers the same type of deposit protection.
Before depositing significant savings, verify who holds your money and what protection applies.
7. Check the Bank’s Accessibility
A high APY is not very useful if the account is difficult for you to use.
Consider whether you prefer:
- Mobile banking
- Online banking
- Physical branches
- ATM access
- Customer support
- Easy transfers
- Simple account management
If you are comfortable with online banking, an online savings account may be convenient.
If you regularly need branch access, however, you may value a bank with physical locations.
Choose the account that fits your actual habits.
How to Compare High Yield Savings Accounts
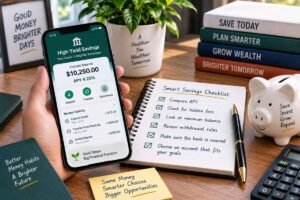
Once you have found several accounts, create a simple comparison.
You can use a table like this:
| Feature | Account A | Account B | Account C |
|---|---|---|---|
| APY | Check current rate | Check current rate | Check current rate |
| Monthly fee | Check terms | Check terms | Check terms |
| Minimum opening deposit | Check terms | Check terms | Check terms |
| Minimum balance | Check terms | Check terms | Check terms |
| Withdrawal rules | Check terms | Check terms | Check terms |
| Online banking | Yes/No | Yes/No | Yes/No |
| Deposit insurance | Verify | Verify | Verify |
This makes it easier to see the differences.
You do not need a complicated spreadsheet.
A simple comparison can prevent you from choosing an account based only on a flashy advertised rate.
Don’t Choose an Account Based Only on the Highest APY
This is one of the most important lessons for beginners.
Imagine Account A offers a slightly higher APY but has a monthly fee that you cannot avoid.
Account B offers a slightly lower APY but has no monthly maintenance fee and easier access to your money.
The second account could potentially be more suitable depending on your balance and how you use the account.
The point is not that one feature is always more important than another.
The point is to compare the whole account.
Interest rate, APY, fees, minimum balances, access, and insurance should all be considered together.
How Much Should You Keep in a High Yield Savings Account?
There is no single amount that everyone should keep in a high yield savings account.
If you are working with a limited income, these practical strategies can also help you save money on a low income while building your savings.
Your savings goal should determine how much you keep there.
For example, you might use one for:
Emergency Savings
An emergency fund is money set aside for unexpected expenses such as urgent repairs, temporary loss of income, or other financial emergencies.
Keeping this money in a savings account can make sense because you want it to remain accessible rather than putting all of it into investments.
Short Term Goals
You could also use a high yield savings account for a goal that is coming up relatively soon.
Examples include:
- A planned purchase
- Education expenses
- Travel
- Moving costs
- A future bill
The important thing is to keep the money separated from your everyday spending when possible.
High Yield Savings Account vs. Regular Savings Account
The basic difference is usually the interest rate.
A traditional savings account may offer a lower rate, while a high yield savings account may offer a more competitive rate.
But the exact difference depends on the financial institutions and accounts you compare.
Do not automatically assume that every high yield account is better.
Keeping your spending and savings separate is also part of learning how to manage your money effectively.
Compare the APY, fees, requirements, accessibility, and other features.
The right account is the one that works well for your particular savings needs.
High Yield Savings Account vs. Checking Account
A checking account is generally designed for everyday transactions.
You might use it for:
- Paying bills
- Debit card purchases
- Regular spending
- Receiving income
- Everyday transfers
A savings account is more focused on setting money aside and earning interest.
This is why some people use both.
For example:
Checking account: Everyday spending
High yield savings account: Emergency fund and savings goals
This separation can also make it easier to avoid accidentally spending money that you intended to save.
Common Mistakes Beginners Should Avoid
Chasing the Highest Rate
The highest APY is not automatically the best choice.
Always look at the complete account terms.
Ignoring Fees
A fee can reduce your actual benefit from the account.
Read the fee schedule before opening it.
Not Checking Requirements
Make sure you understand minimum balances, deposit requirements, withdrawal rules, and other conditions.
Keeping Too Much Money in One Place
Depending on your circumstances and the applicable deposit insurance rules, you may need to think about how your deposits are protected and whether spreading funds across institutions is appropriate.
Forgetting That Rates Can Change
Savings account rates can change over time.
Do not assume the rate you see today will remain the same indefinitely.
Check your account periodically and compare alternatives when necessary.
Using Savings for Everyday Spending
If you constantly move money out of your savings account for daily purchases, you may be using the wrong account for that purpose.
Keep everyday spending and savings separate when possible.
A Simple Step by Step Process for Choosing Your Account
If all of this feels complicated, use this simple process.
Step 1: Decide What the Money Is For
Are you saving for emergencies, a short-term goal, or something else?
Step 2: Find Several Accounts
Look at several banks or financial institutions rather than choosing the first account you see.
Step 3: Compare APYs
Check the current APY and understand whether any conditions apply.
Step 4: Check Fees
Look for monthly maintenance fees, withdrawal fees, transfer fees, and other charges.
Step 5: Check Minimums
Look at both the minimum opening deposit and any minimum balance requirements.
Step 6: Check Access
Make sure you can easily move or access your money when necessary.
Step 7: Verify Deposit Protection
Confirm what type of deposit insurance or protection applies to the institution and account.
Step 8: Read the Terms
Before opening the account, read the important account disclosures.
This final step can help you discover conditions that may not be obvious from an advertisement.
Final Thoughts
Learning how to choose a high yield savings account for beginners does not have to be complicated.
Start with the basics.
Compare the APY, check the fees, understand minimum balance requirements, review withdrawal rules, consider accessibility, and verify deposit protection.
Most importantly, do not choose an account simply because it advertises the highest rate.
Your goal should be to find an account that helps your savings earn interest while fitting your financial needs and habits.
If you are also working on organizing your monthly finances, you can learn more about the 50/30/20 budget rule and how it can help you divide your income between needs, wants, and savings.
Take your time, compare several options, and read the account terms before making a decision. A few minutes of research can help you avoid unnecessary fees and choose a savings account that makes sense for your goals.
Frequently Asked Questions
What is a high yield savings account?
A high yield savings account is a savings account that generally offers a higher interest rate than many traditional savings accounts. The exact rate and terms vary by financial institution.
Is a high yield savings account safe?
Safety depends on the institution, account type, and applicable deposit protection. In the United States, eligible deposits at FDIC insured banks are generally protected up to the applicable FDIC insurance limit. Always verify the institution’s insurance status before depositing money.
What is the difference between APY and interest rate?
The interest rate shows the stated rate paid on the balance, while APY takes the effect of compounding into account and expresses the annual yield. APY is therefore useful when comparing deposit accounts.
Can I withdraw money from a high yield savings account?
Usually, yes, but the exact withdrawal and transfer rules depend on the account. Some institutions may charge fees or apply limits to certain transactions, so check the account terms before opening it.
Should I choose the savings account with the highest APY?
Not necessarily. Compare the APY together with fees, minimum balance requirements, withdrawal rules, accessibility, and deposit protection.
How much money should I keep in a high yield savings account?
There is no universal amount. It can be used for emergency savings, short term goals, or other money you want to keep accessible while earning interest.
Can a high yield savings account lose money?
A normal savings account is different from an investment account because you are depositing money rather than buying market investments. However, account terms, fees, applicable insurance limits, and the financial institution still matter. Always verify the protections that apply to your account.
Should beginners have both a checking and savings account?
Many people find it useful to separate everyday spending from savings. A checking account can handle regular transactions, while a savings account can be used for money you want to set aside.